
Custom Health Plans, Inc. Helps Self-Employed Texans Find Private Health Insurance Beyond the Marketplace
Custom Health Plans, Inc. offers expert guidance on off-exchange plans, PPO coverage, and association health plans for independent workers and small business owners.
Plano, TX , Sept. 25, 2026 (GLOBE NEWSWIRE) -- Custom Health Plans, Inc., a full-service Texas health insurance broker based in Plano, helps self-employed individuals, independent contractors, and small business owners navigate health insurance alternatives beyond the Marketplace.
The firm specializes in connecting Texas clients with private PPO coverage, association health plans, and ICHRA arrangements. These are designed to provide greater flexibility and cost predictability than traditional group plans.
Most self-employed workers and small business owners assume the Marketplace represents their only option for health coverage. Custom Health Plans, Inc. is shifting that narrative by educating Texas's independent workforce about coverage paths rarely discussed: off-exchange health insurance, private PPO plans, and association health plans. The firm's approach centers on comparing all available options rather than defaulting clients to federal exchange solutions.
The distinction matters significantly. Health insurance for self-employed Texas residents extends well beyond what appears on HealthCare.gov. Custom Health Plans guides clients through non-marketplace health insurance options, including direct individual plans purchased from carriers, association health plans that pool self-employed workers for negotiating power, and an emerging solution called Individual Coverage Health Reimbursement Arrangements (ICHRA) that fundamentally reshapes how employers fund employee health benefits.
Custom Health Plans, Inc.
"Our role is demystifying coverage options that exist in the shadows of mainstream discussion," said Richard Monello, President/CEO of Custom Health Plans.
How Custom Health Plans, Inc. Serves Self-Employed Workers and Small Business Owners
The company's methodology rests on comprehensive carrier comparison and personalized plan matching. Rather than steering clients toward predetermined solutions, advisors conduct detailed consultations exploring medical history, anticipated healthcare use, budget constraints, and coverage preferences. This process reveals which small business health insurance in Texas aligns with individual circumstances—whether that's a high-deductible plan paired with health savings account contributions, comprehensive PPO coverage for frequent medical needs, or association-based group plans offering cost advantages for eligible business owners.
Association health plans represent one underutilized option the firm emphasizes. These plans allow self-employed individuals and small business operators to band together through professional or industry associations, accessing group rates typically reserved for larger employers.
Custom Health Plans connects eligible clients with association memberships that unlock substantial savings while maintaining quality networks and benefit structures. For independent contractors and micro-businesses across Dallas, Fort Worth, Austin, Houston, San Antonio and surrounding regions, this pathway often delivers superior value compared to individual marketplace plans.
Private PPO networks offer another distinction worth understanding. Unlike marketplace silver, gold, and platinum tiers, private plans may feature different deductible structures, prescription formularies, and provider networks. Some designs emphasize preventive care access while maintaining higher catastrophic coverage limits. Others prioritize lower monthly premiums for clients comfortable with higher out-of-pocket expenses.
For owners of small business health insurance in Texas, traditional group plans have long been the default, but at a cost. Annual premium increases of 5-10 percent are common, participation requirements lock out flexibility, and employers must accept whatever plan options insurers offer. ICHRA flips this model entirely. Rather than purchasing a company-wide plan, employers set a fixed monthly budget and employees select their own coverage from the open market.
ICHRA works particularly well for employers seeking simplicity without sacrificing choice. An employer in the Dallas-Fort Worth area might set a $500 monthly contribution for full-time employees. Workers then browse individual plans on the ACA Marketplace, direct carrier websites, or through brokers. They submit proof of their selected plan's cost, and the employer reimburses them up to the $500 limit, tax-free to both parties.
For those with no employees, direct individual policies and association health plans emerge as the primary health insurance for self-employed Texas residents. Each policy has specific tax treatment and subsidy eligibility rules that require careful analysis.
Understanding ICHRA vs. Traditional Group Plans: A Side-by-Side Look
The fundamental difference between ICHRA and traditional group insurance boils down to control and predictability. Traditional group plans force employers into a reactive position: insurers announce annual rate increases, networks shift, and employees accept whatever options leadership selected.
Participation requirements represent another critical distinction. Traditional group plans in Texas typically require 70 percent or higher employee participation to avoid unfavorable underwriting. ICHRA has no such mandate.
Flexibility extends to plan type as well: employees buying through the Marketplace access all four metal tiers (Bronze, Silver, Gold, Platinum); those purchasing directly from carriers can select any available product; those choosing association health plans access specialized coverage designed for self-employed and small business demographics.
Custom Health Plans Key Features and Facts
- Service Areas: Established Texas presence spanning Austin, Dallas, Houston, San Antonio, Fort Worth, Plano, and surrounding communities; recent expansion into Florida
- Core Offerings: Full-service health insurance brokerage, ICHRA administration guidance, private PPO placement, association health plan enrollment, and Marketplace alternatives consultation
- Track Record: 30+ years in health insurance consulting; 1000+ Texas clients successfully matched with customized coverage
- Availability: Expert advisors available for consultations and plan selection guidance throughout enrollment periods and life-change events
Frequently Asked Questions
Q: What makes off-exchange plans different from Marketplace options?
A: Off-exchange health insurance plans bypass federal enrollment requirements and standardized benefit design, allowing carriers to structure coverage with greater flexibility. These plans may offer different deductible levels, provider networks, and cost-sharing arrangements than Marketplace alternatives.
Q: Are association health plans genuinely available for solo business owners?
A: Yes, association health plans allow self-employed individuals meeting specific criteria to access group coverage rates through professional or industry memberships. Eligibility varies by association and state regulations, which Custom Health Plans' advisors assess during initial consultation.
Q: How do private PPO plans affect provider choice and costs?
A: Private PPO networks may differ from Marketplace plan networks in participating providers and cost-sharing structures. Custom Health Plans compares specific networks against client healthcare patterns to identify plans maximizing both affordability and provider access.
Q: Can self-employed individuals access ICHRA?
A: No, ICHRA requires an employer-employee relationship, but self-employed professionals can purchase private PPO coverage or join association health plans to achieve similar flexibility and cost control.
Q: How do I start exploring my actual health insurance options?
A: Contact Custom Health Plans, Inc. through its website or phone line to schedule an initial consultation with an advisor.
Visit https://www.customhealthplans.com/ to learn more about coverage options.
About Custom Health Plans, Inc.
With over 30 years of industry experience, Custom Health Plans, Inc. specializes in matching self-employed workers, small business owners, and independent contractors with personalized health coverage solutions. The firm has helped 1000+ Texas clients through ICHRA arrangements, private PPO coverage, association health plans, and other non-marketplace health insurance alternatives designed to maximize flexibility and cost predictability.
Visit www.customhealthplans.com for details.
###
Contact
Custom Health Plans, Inc.
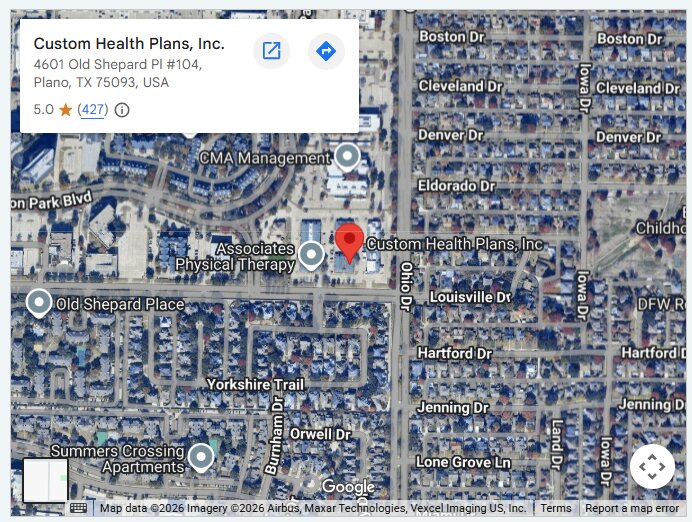
4601 Old Shepard Pl #104, Plano, TX 75093
469-361-4032
Social Media
Facebook: www.facebook.com/customhealthplans
LinkedIn: https://www.linkedin.com/in/thehsaguy/
Map Link: maps.google.com/maps?cid=15763311492464511837
YouTube: www.youtube.com/channel/UCe6UnUh-RP3GY7AbYqHKDUg
Instagram: www.instagram.com/customhealthplans/
Disclaimer: This release is provided for general informational purposes only and does not constitute insurance, tax, legal, or financial advice. Health plan availability, eligibility, benefits, costs, tax treatment, and regulatory requirements vary by plan and individual circumstances. Consumers and employers should review applicable plan documents and consult a licensed insurance professional or other qualified adviser before making coverage decisions.
Attachment


Custom Health Plans, Inc. Helps Self-Employed Texans Find Private Health Insurance Beyond the Marketplace

Custom Health Plans, Inc. offers expert guidance on off-exchange plans, PPO coverage, and association health plans for independent workers and small business owners.
Legal Disclaimer:
EIN Presswire provides this news content "as is" without warranty of any kind. We do not accept any responsibility or liability for the accuracy, content, images, videos, licenses, completeness, legality, or reliability of the information contained in this article. If you have any complaints or copyright issues related to this article, kindly contact the author above.
